
Key Points:
- Canada’s six largest banks are exploring a shared Canadian-dollar tokenized deposit system designed to move commercial deposits more efficiently between participating institutions.
- The initial phase will focus on interbank transfers, with a longer-term objective of connecting the system to broader digital-asset initiatives and supporting programmable, around-the-clock payments.
- The project follows Canada’s C$100 million tokenized-bond experiment under Project Samara and reflects a wider global move by banks toward blockchain-based payment infrastructure.
Canada’s six largest banks are joining the global push to put commercial bank deposits on blockchain infrastructure, exploring a shared system for moving Canadian-dollar deposits between financial institutions. The initiative places tokenized bank money at the center of Canada’s digital-finance strategy while potentially creating a regulated bridge between conventional banking infrastructure and the wider digital-asset ecosystem.
Big Six Banks Test a Shared Tokenized-Deposit Model
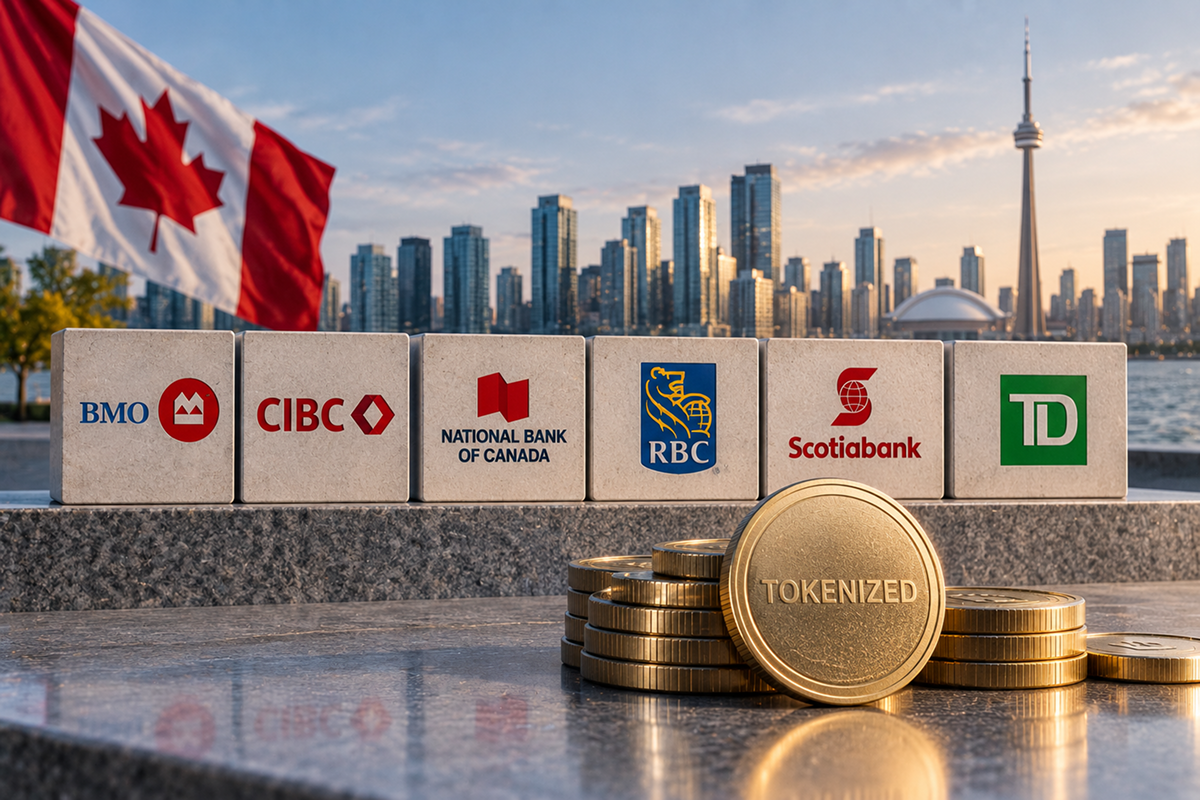
The initiative brings together Bank of Montreal, Canadian Imperial Bank of Commerce, National Bank of Canada, Royal Bank of Canada, Scotiabank and TD Bank Group. The banks said the first phase will focus on moving tokenized deposits efficiently across participating institutions, with additional banks potentially joining the project later.
Unlike privately issued stablecoins, tokenized deposits represent digital versions of money already held as bank deposits. The model therefore keeps the underlying customer funds within the regulated banking system while using distributed-ledger infrastructure to potentially improve transfer speed, programmability and settlement availability.
The distinction is important for institutional crypto markets. Rather than moving deposits into a separate digital-asset issuer, businesses could eventually use blockchain-based representations of commercial bank money while maintaining their existing banking relationships.
Interbank Payments Are the First Use Case
The initial focus is deliberately narrow: interbank movement of tokenized deposits. The participating banks said the system is intended to support faster, more efficient and programmable payments while preserving financial stability and regulatory oversight.
That architecture could eventually support transactions outside traditional banking hours. A shared ledger could allow participating institutions to synchronize payment obligations and settle transactions using digital representations of commercial-bank money, reducing some of the reconciliation and intermediary processes associated with conventional payment rails.
The longer-term objective is to connect the banking system with other emerging digital-asset initiatives. However, the banks have not committed to issuing a tokenized deposit, meaning the current announcement represents an exploration and testing phase rather than a confirmed commercial launch.
Canada Already Has a Tokenized-Bond Test
The project builds on earlier Canadian experimentation with distributed-ledger financial infrastructure. In March, the Bank of Canada, RBC, TD and Export Development Canada completed Project Samara, issuing, trading and settling a C$100 million tokenized bond using distributed-ledger technology and wholesale central-bank money.
The experiment demonstrated that tokenized securities could operate through an integrated securities and cash ledger, although the Bank of Canada also identified system complexity, liquidity costs and governance requirements as limitations that need to be addressed before broader deployment.
Canada has also joined the BIS’s Project Agorá, which is testing tokenized commercial-bank deposits alongside wholesale central-bank money for cross-border payments. The initiative is examining whether programmable settlement can improve speed, efficiency and transparency while operating within existing legal and regulatory frameworks.
Global Banking Is Moving in the Same Direction
Canada’s initiative arrives as major banks elsewhere are testing similar infrastructure. In the United States, banks are developing shared tokenized-deposit networks, while JPMorgan, Citi and Wells Fargo are pursuing institutional tokenization initiatives. Swift has also begun testing tokenized deposits for 24/7 cross-border payments, with 17 banks participating in its broader pilot.
For crypto investors and institutions, the important development is the growing convergence between commercial-bank deposits and blockchain settlement. If Canada’s Big Six eventually move from experimentation to production, tokenized deposits could become another regulated payment rail operating alongside stablecoins and other digital assets. The next milestones will be actual transaction testing, interoperability with external networks and evidence that the infrastructure can deliver measurable efficiency gains without creating new liquidity, governance or operational risks.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible