
Key Points:
- Stablecoins are evolving beyond cryptocurrency trading, with potential applications in payments, cross-border transfers, treasury operations and blockchain-based financial services.
- Regulatory clarity is becoming central to institutional adoption, as financial advisors assess issuer oversight, reserve backing, custody and redemption arrangements.
- Operational benefits must be weighed against risks, including issuer failure, technology vulnerabilities, liquidity constraints and the absence of deposit insurance for many stablecoin holdings.
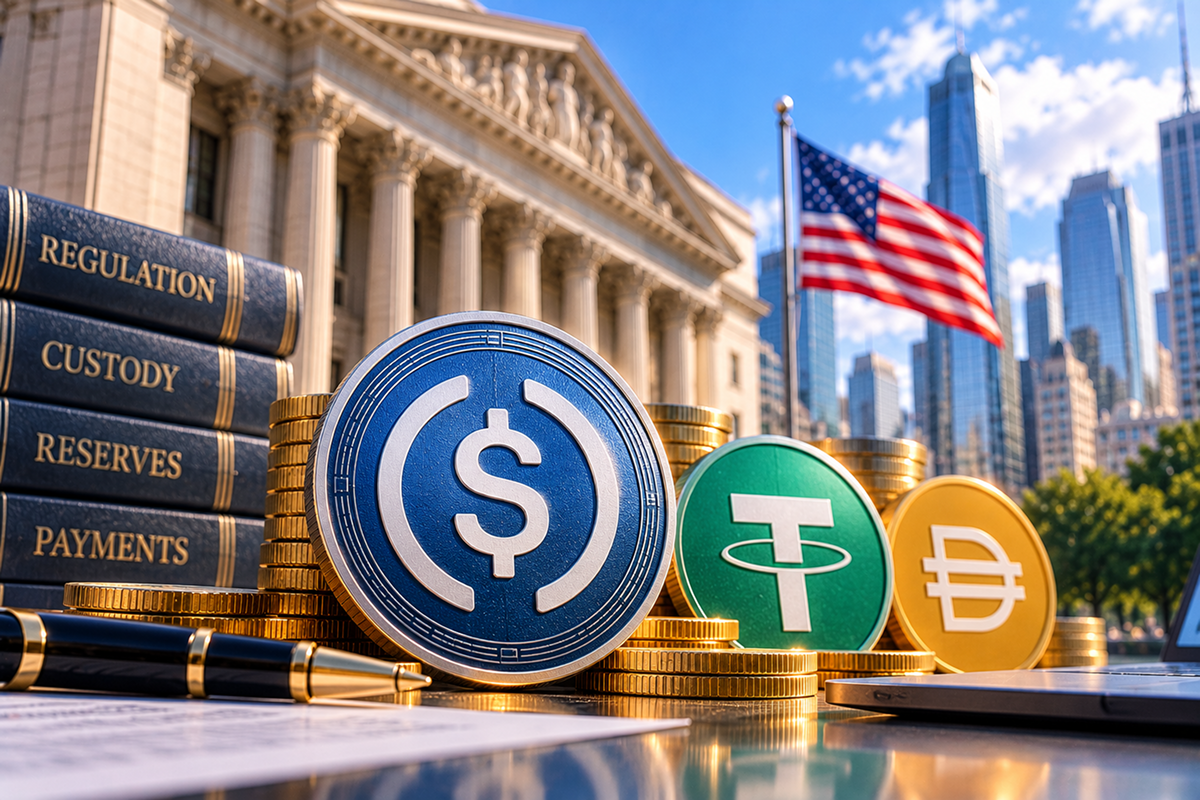
Stablecoins are increasingly attracting attention as financial infrastructure rather than simply instruments used to move between cryptocurrencies. For financial advisors serving clients who expect efficient payments, transparent asset management and reliable access to funds, dollar-pegged digital tokens present a developing opportunity—but also a new set of due-diligence requirements. As regulation evolves and traditional financial institutions explore blockchain-based services, the key question is whether stablecoins can deliver practical benefits while meeting institutional standards for risk management and client protection.
From Crypto Trading to Financial Infrastructure
Stablecoins are digital tokens designed to maintain a relatively stable value by referencing an asset such as the U.S. dollar. Unlike Bitcoin, whose market price fluctuates with supply, demand and investor sentiment, a dollar-pegged stablecoin aims to maintain a value close to one dollar through its reserve and redemption arrangements.
This structure makes stablecoins potentially useful for transferring value, settling transactions and holding digital dollars between investment activities. Businesses may also use them to explore faster cross-border payments and blockchain-based treasury processes. Transactions can occur on blockchain networks without relying entirely on traditional banking hours, although actual settlement speed and cost depend on the network, service provider and conversion process.
For advisors, the significance is that stablecoins may become part of the financial technology used by clients and institutions—not merely an additional cryptocurrency exposure. However, their usefulness depends on whether the infrastructure offers measurable improvements over conventional payment and cash-management systems.
Regulation and Reserve Quality Shape Institutional Confidence
Regulatory requirements are an important factor in determining whether stablecoins can gain broader acceptance. In the United States, the GENIUS Act, signed into law in July 2025, established a federal framework for payment stablecoins, including requirements for full reserve backing with eligible liquid assets and regulatory oversight.
Implementation remains important. Advisors and institutions need to understand who issues a token, what assets support its value, how reserves are managed and what procedures apply when holders seek redemption. A stablecoin’s target price of one dollar is not, by itself, a guarantee that every holder can redeem immediately under all circumstances.
Due diligence should also distinguish the stablecoin issuer from the exchange, custodian or payment platform through which a client accesses it. Different entities may carry different obligations, and the legal rights available to holders depend on the product and jurisdiction.
Efficiency Comes With Custody and Operational Risks
Stablecoins may reduce friction in certain payment and settlement processes, but efficiency should not be confused with risk-free operation. Blockchain transactions can be difficult or impossible to reverse, smart contracts may contain vulnerabilities, and access can be disrupted by technical failures or service-provider problems.
There are also financial risks. Reserve assets, redemption mechanisms and the issuer’s operational resilience all affect confidence in a token’s peg. Stablecoins generally do not provide the same protections as insured bank deposits, and holders may face losses or delays if an issuer or intermediary encounters serious difficulties.
Advisors evaluating a stablecoin service should therefore examine custody arrangements, redemption terms, transaction costs, compliance controls and the process for recovering assets if a platform fails. The relevant question is not simply whether the token is pegged to the dollar, but whether the entire system is suitable for the intended use.
What Financial Advisors Should Monitor Next
Stablecoin adoption will depend on the interaction between regulation, market infrastructure and demonstrated customer demand. Financial advisors should watch how issuers disclose reserve information, how supervisory rules are implemented and whether payment providers can show consistent improvements in cost, settlement speed and reliability.
Stablecoins may become an increasingly practical component of digital finance, but mainstream use requires more than technological capability. Transparent reserves, enforceable redemption rights, sound custody and clear accountability will determine whether these digital dollars earn lasting institutional confidence. For advisors, understanding both the potential efficiencies and the limitations is essential as stablecoins move closer to everyday financial operations.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible