
Key Points:
- New Digital Securities Infrastructure: Bank Negara Malaysia has launched SSDS+, a distributed ledger technology (DLT) platform supporting the issuance, custody and transfer of tokenized debt securities, including Islamic sukuk.
- Settlement in Central Bank Money: The platform connects securities ownership records with RENTAS+, enabling corresponding payments to be settled in central bank money.
- Part of a Broader Tokenization Strategy: The launch follows Malaysia’s three-year asset tokenization roadmap and earlier trials involving ringgit stablecoins and tokenized bank deposits.
Malaysia Advances Tokenized Bond Infrastructure
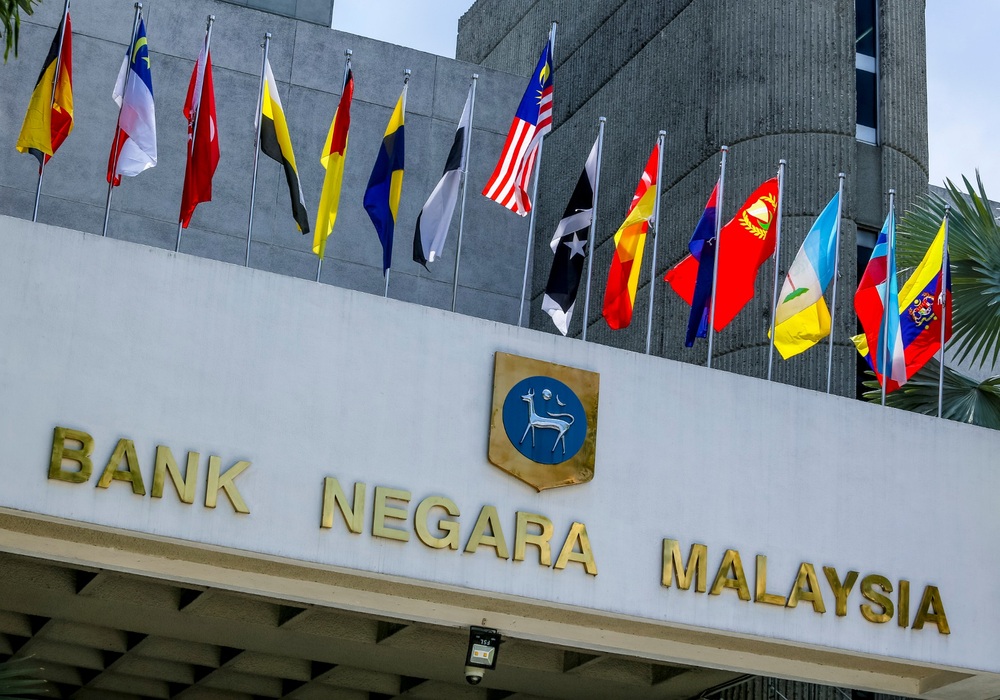
Malaysia’s central bank has introduced a distributed ledger-based platform designed to modernize the issuance and management of debt securities. The initiative expands the country’s digital financial infrastructure, connecting tokenized securities records with a payment system that supports round-the-clock operations.
Bank Negara Malaysia (BNM) announced that its next-generation Scripless Securities Depository System, known as SSDS+, supports the issuance, depository and safekeeping of tokenized debt securities, including sukuk, which are Islamic financial instruments structured to comply with Sharia principles.
The platform is designed to record securities ownership and transfers on distributed ledger infrastructure. By linking those records to the country’s payment settlement system, Malaysia aims to connect digital securities transactions with established financial settlement arrangements.
Connecting Tokenized Securities With Central Bank Money
A central feature of SSDS+ is its integration with RENTAS+, the Real Time Electronic Transfer of Funds and Securities system. The connection allows payments associated with tokenized securities transactions to be settled in central bank money.
This arrangement links the digital record of securities ownership with the movement of funds, addressing a core requirement for institutional adoption of tokenized financial assets. Settlement in central bank money also provides a framework for completing the payment leg of a transaction through the central bank’s settlement infrastructure.
Although the platform was designed primarily for wholesale issuance, BNM said it is also prepared to support tokenized government bonds and corporate retail bonds. This broader capability could provide a foundation for expanding tokenization beyond institutional debt markets.
However, the announcement did not identify securities already issued through SSDS+ or disclose transaction volumes. The platform’s initial adoption, the range of instruments issued and the scale of activity therefore remain unclear.
Building on Malaysia’s Tokenization Roadmap
The launch follows a three-year asset tokenization roadmap unveiled by BNM in November 2025. The roadmap outlined planned pilot projects across Islamic finance, supply chain financing and programmable payments, positioning tokenization as part of a wider effort to explore new financial infrastructure.
The central bank also tested ringgit stablecoins and tokenized bank deposits through its Digital Asset Innovation Hub in February. Participants included Standard Chartered, CIMB Group, Maybank and investment holding company Capital A.
Together, these initiatives indicate that Malaysia is examining tokenization across several layers of the financial system, from securities issuance and settlement to digital representations of deposits and payment instruments.
The approach also places emphasis on connecting new digital asset infrastructure with established financial systems rather than treating tokenization as a separate market. For banks and other financial institutions, that integration may be important to evaluating operational efficiency, settlement processes and the potential use of programmable financial products.
Outlook
SSDS+ gives Malaysia a dedicated foundation for tokenized debt securities, with central bank money settlement providing a link between digital ownership records and payment infrastructure. The next indicators to watch are actual issuance activity, participation by financial institutions and whether the platform expands into government and corporate retail bonds. Adoption across these areas will help determine whether the initiative develops into a meaningful component of Malaysia’s broader digital finance strategy.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible