
Key Points:
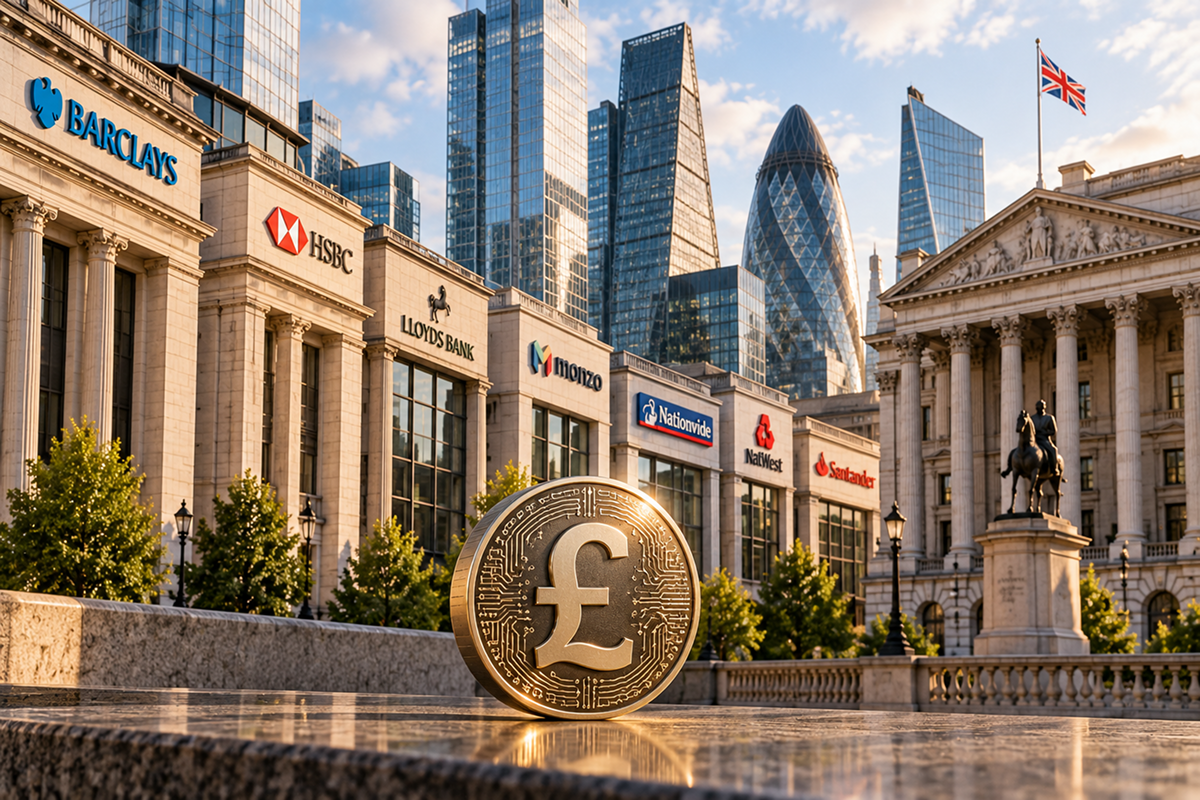
- Seven major UK banks, including Barclays, HSBC, Lloyds, Monzo, Nationwide, NatWest and Santander, completed live customer transactions using tokenized sterling deposits on a shared platform.
- The pilot covered two remortgage transactions and a programmable marketplace payment, demonstrating that tokenized commercial bank money can move between separate institutions rather than remaining within one bank’s system.
- The project is expected to expand into digital-asset settlement and three digital bonds in early 2027, potentially linking tokenized bank money with the emerging market for tokenized securities.
Britain’s largest banks have completed what the industry describes as the world’s first live interbank customer transactions using tokenized deposits, marking a significant step in the development of blockchain-based commercial bank money. The transactions demonstrate that digital representations of sterling deposits can move between separate banks, bringing tokenized money closer to practical payment and securities-settlement infrastructure.
Tokenized Deposits Move Beyond Single-Bank Systems
The Great British Tokenized Deposit initiative, convened by UK Finance, brings together seven major banks: Barclays, HSBC UK, Lloyds Banking Group, Monzo, Nationwide, NatWest and Santander. The shared infrastructure was built by Quant, with EY providing project management and Linklaters supporting the legal framework and rulebooks.
The significance is interoperability. Banks have experimented with tokenized deposits for years, but many previous projects operated within individual institutions, limiting their usefulness when customers at different banks needed to transact. The latest pilot tests whether regulated commercial bank money can move across institutional boundaries while retaining its status as a bank deposit.
Remortgages Demonstrate Programmable Settlement
Lloyds, NatWest and Barclays completed two remortgage transactions using tokenized deposits. Funds were effectively locked during the transaction process and automatically released when the required conditions were met, demonstrating how programmable money could reduce manual settlement steps and potentially shorten transaction timelines.
A separate test involved three banks, including HSBC, simulating a person-to-person payment linked to an online marketplace purchase. The buyer’s funds could remain reserved until the agreed conditions were satisfied, after which the payment was released to the seller. No physical goods changed hands because the marketplace transaction was simulated.
For financial institutions, the use cases matter because tokenization is being tested against ordinary banking activity rather than solely against cryptocurrency trading or experimental blockchain applications.
Tokenized Deposits Compete With Other Forms of Digital Money
Tokenized deposits differ from stablecoins in their underlying structure. A tokenized deposit represents commercial bank money and remains a liability of the issuing bank, whereas a stablecoin is generally issued by a private company against reserve assets. The UK banking model therefore seeks to bring blockchain functionality into the existing regulated deposit framework.
The Bank of England has supported experimentation with tokenized deposits while regulators continue developing frameworks for stablecoins, tokenized securities and digital settlement. The distinction could become increasingly important as banks seek blockchain-based payment infrastructure without moving deposits outside the regulated banking system.
Digital Bonds Are the Next Institutional Test
The project is already looking beyond payments. UK Finance plans to establish a company and governance framework for the initiative, while participating banks expect to issue three digital bonds in early 2027 that can be traded and settled using tokenized deposits.
That next stage could be more significant for digital-asset markets because it would connect tokenized commercial bank money with tokenized securities. For sophisticated crypto investors, the key indicators will be transaction volumes, interoperability across banks, regulatory treatment and whether tokenized deposits can provide efficient settlement for digital assets at institutional scale.
The UK initiative remains a pilot rather than a full-scale replacement for existing payment infrastructure. Its importance lies in demonstrating that regulated bank money can operate across institutional boundaries on shared blockchain infrastructure. If subsequent digital-bond and digital-asset settlement trials produce measurable efficiency gains, tokenized deposits could become an important bridge between traditional banking and institutional digital-asset markets.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible